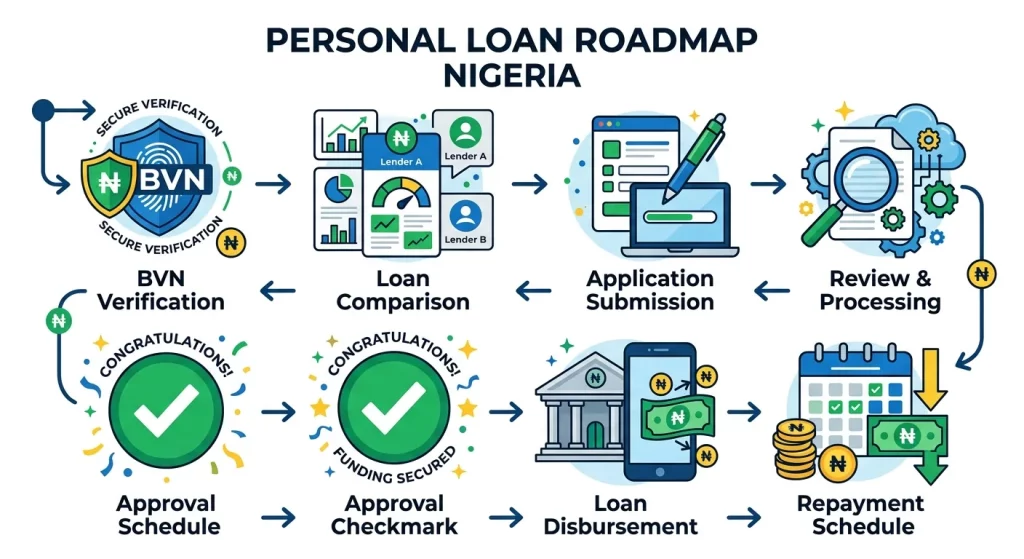
This guide covers everything: what a personal loan in Nigeria actually involves, who qualifies, where to get one safely, what it truly costs in real ₦ numbers, and how to avoid the traps that keep borrowers stuck in a cycle they cannot escape.
What Is a Personal Loan in Nigeria?
A personal loan is cash you borrow from a lender — a bank, microfinance institution, or loan app — for any personal need. Not a business, not trading stock. Personal needs like:
- Rent when your landlord won’t wait another week
- School fees expiring on Friday
- A hospital bill your NHIS didn’t fully cover
- Replacing a phone or tool that is costing you daily income
- Transport, food, and data running out five days before payday
- Sending money home for a family emergency
You receive the cash, use it, and repay in agreed instalments — usually within 1 to 12 months — plus interest. No collateral required in most cases. No long queues. Just your BVN and a lender willing to approve you.
Personal Loan vs Other Loan Types: Quick Clarity
| Loan Type | What It’s For | Who Offers It |
|---|---|---|
| Personal loan | Any individual need — bills, emergencies, rent | Banks, loan apps, MFBs |
| Salary advance | Bridge your own salary early | Employer, HR fintech |
| Business loan | Working capital, trade, stock | Banks, SME lenders |
| BNPL | Buy specific product now, pay later | Retailers, fintech |
| Payday loan | Ultra-short bridge to next payday | Loan apps |
If you need cash for your life — not a business — a personal loan Nigeria providers offer is almost certainly what you are looking for.
Who Qualifies for a Personal Loan in Nigeria?
The eligibility bar in 2026 is lower than most people think — especially through loan apps.
Common requirements across most lenders:
- Nigerian citizen, 18 years and above
- Valid BVN (Bank Verification Number)
- Active Nigerian bank account
- Verifiable income — salary, trade, artisan work, or gig income
- A smartphone for app-based lenders
Some lenders check your credit score through CRC Credit Bureau or FirstCentral. A poor score doesn’t automatically disqualify you — but it affects your limit and interest rate.
What disqualifies most applicants:
- Defaulting on a previous loan without repaying — your BVN flags this across all lenders
- No verifiable bank transaction history
- Providing false information during application
- An active credit bureau blacklist entry
Where to Get a Personal Loan in Nigeria (2026 Options)
You have four main channels for a personal loan Nigeria borrowers commonly use. Each has real tradeoffs.
1. Loan Apps — Fastest and Most Accessible
Apps like LendSafe, Carbon, Palmcredit, and Branch have transformed personal lending in Nigeria. Apply on your phone, upload documents, receive a decision — sometimes in under 30 minutes. The FCCPC’s 2023 consumer credit report found over 40 million Nigerians have accessed at least one digital loan product.
Best for: Urgent needs, people without payslips, thin credit files
Watch for: Monthly interest rates ranging from 3% to 30% — always verify app registration with the CBN or FCCPC before submitting your BVN
2. Microfinance Banks (MFBs)
Over 900 licensed MFBs operate across Nigeria per the CBN’s 2024 supervised institutions list. They serve low-to-middle income Nigerians specifically — market traders, artisans, domestic workers, corps members. Rates tend to be lower but approval takes 2–5 business days.
Examples: LAPO Microfinance Bank, Accion MFB, AB Microfinance Bank
3. Commercial Banks
GTBank’s QuickCredit, Access Bank’s Payday Loan, and Zenith Bank’s term loan products serve salary account holders at those specific banks. Fast and structured — but you must already bank with them and receive a verifiable monthly salary.
Not ideal for: Market traders, artisans, gig workers, self-employed Nigerians
4. Cooperative Societies
If your workplace, church, or community has a registered cooperative, this is often the cheapest personal loan source in Nigeria — rates of 1–2% per month, flexible repayment, rare penalty clauses.
Downside: You must already be a registered member. Not useful for this week’s emergency.
What Does a Personal Loan Actually Cost in Nigeria?
This is where most people get hurt — they focus on the loan amount, not total repayment.
Key cost components:
- Interest rate: Always convert to monthly to compare lenders fairly
- Processing fee: Typically 1–5%, deducted before you receive funds
- Late payment penalty: Can be 1–5% per day of default — this is where debt spirals start
- Insurance fee: Some lenders add this quietly — always check your full breakdown
Real ₦ Calculation:
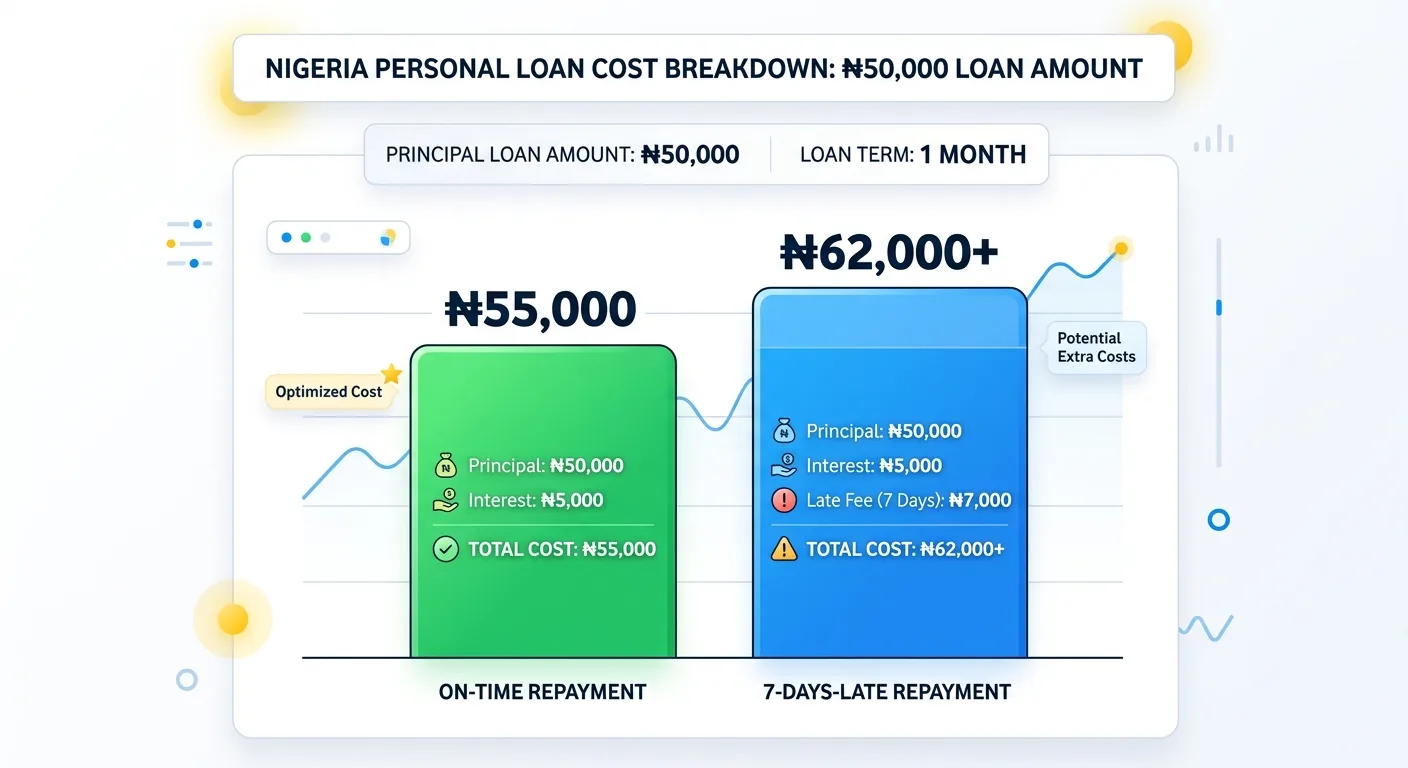
You borrow ₦50,000 for 30 days at 10% monthly interest with a 2% processing fee:
- Processing fee deducted upfront: ₦1,000 → you receive ₦49,000
- Interest owed at repayment: ₦5,000
- Total repayment: ₦55,000 on a loan that gave you ₦49,000
That is an effective cost of ₦6,000 on ₦49,000 — approximately 12.2% effective cost in 30 days.
Now add a missed repayment. At a 2% daily late fee, three extra days costs another ₦3,000. One full week late? ₦7,000 more. A quick personal loan Nigeria lenders advertise as “₦50,000” can cost ₦62,000+ before you realise what happened.
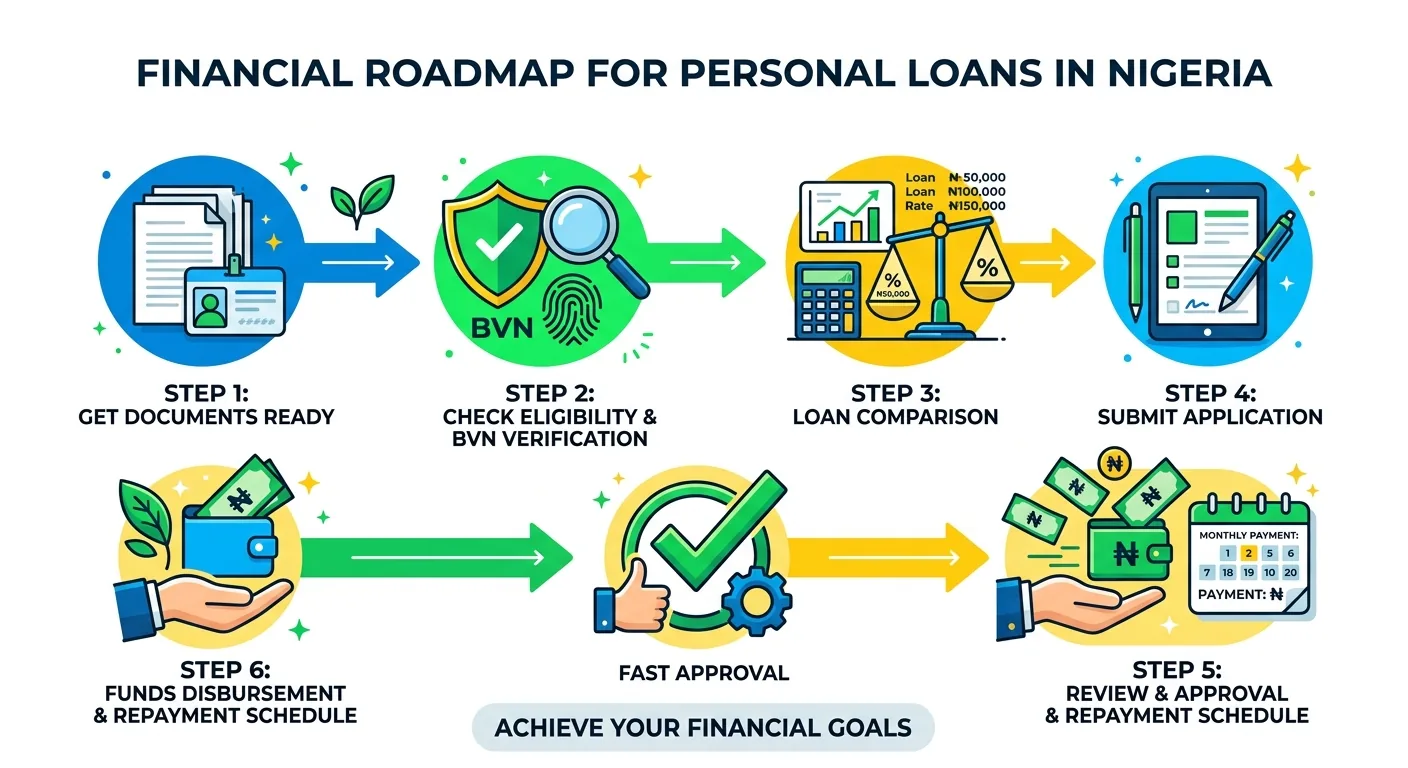
How to Apply for a Personal Loan in Nigeria: Step-by-Step
Step 1: Know exactly how much you need.
Don’t overborrow. Every extra ₦5,000 borrowed costs ₦500–₦1,500 in unnecessary interest.
Step 2: Check your repayment capacity first.
Can you repay the total amount from your next income cycle without being unable to cover transport or food? If not, your loan size is too large.
Step 3: Compare at least 3 lenders.
The same ₦30,000 personal loan Nigeria options can cost ₦33,000 at one lender and ₦39,000 at another. Fifteen minutes of comparison saves real money.
Step 4: Verify the lender is legitimate.
Check the FCCPC consumer credit registry or the CBN licensed institutions list. A lender on neither is a serious red flag — unregistered lenders face zero regulatory consequence for harassing you or accessing your contacts illegally.
Step 5: Apply with accurate information.
Your name, BVN, account number, and income details must match exactly. Mismatches trigger automatic rejection or a credit bureau fraud flag.
Step 6: Read the repayment schedule before confirming.
Know your exact due date. If you are paid on the 25th and your loan is due on the 22nd, that timing gap needs solving now.
Step 7: Repay on time — or communicate early.
Most lenders offer restructuring if you contact them before defaulting. After default, fees stack fast and your BVN record takes a lasting hit.
Bad Credit? Your Honest Reality
A bad credit score changes what personal loan Nigeria lenders will offer you — but it does not shut every door.
What changes with bad credit:
– Lower loan limits: ₦5,000–₦20,000 instead of ₦50,000+
– Higher interest rates — lenders charge more to offset perceived risk
– More income verification requirements
– Outright decline from stricter lenders
What you can still access:
– Several personal loan apps in Nigeria approve first-time borrowers regardless of score
– MFBs often use character-based lending for known community members
– Cooperative societies frequently bypass credit bureau checks entirely
Rebuilding takes 6–12 months of consistent on-time repayments — entirely achievable starting today.
5 Personal Loan Mistakes That Cost Nigerians Money Every Month
1. Borrowing more than you need. Every extra ₦5,000 costs ₦500–₦1,500 in interest. Borrow the exact gap.
2. Ignoring the processing fee. If you need ₦50,000 in hand with a 3% upfront fee, apply for ₦51,550. Otherwise you will be short and tempted to take a second personal loan Nigeria lenders happily approve.
3. Using one loan to repay another. This is the entry point of the debt spiral — restructuring is more urgent than another application.
4. Not verifying lender registration. Loan app scams in Nigeria are real and well-documented. An unregistered lender faces zero regulatory consequence.
5. Forgetting the due date. A ₦30,000 personal loan at 1% daily late fee, missed by 10 days = ₦3,000 extra. Set a phone alarm the moment you accept any personal loan Nigeria terms.
Next Steps:
– 📱 Compare personal loan Nigeria options and apply — decision in minutes
– 🔍 Review the best personal loan apps in Nigeria for 2026
– 📋 Check your credit score before submitting any application
– ⚠️ Verify whether your loan app is FCCPC-registered before sharing your BVN